
Ahmed Barakat is a journalist and copywriter based in Georgia with a growing focus on blockchain technology, DeFi, AI, privacy, digital assets, and fintech innovation.


The CryptoNews editorial team is composed of seasoned writers specializing in cryptocurrency and blockchain technology. Their expertise ensures comprehensive, accurate, and insightful content for…
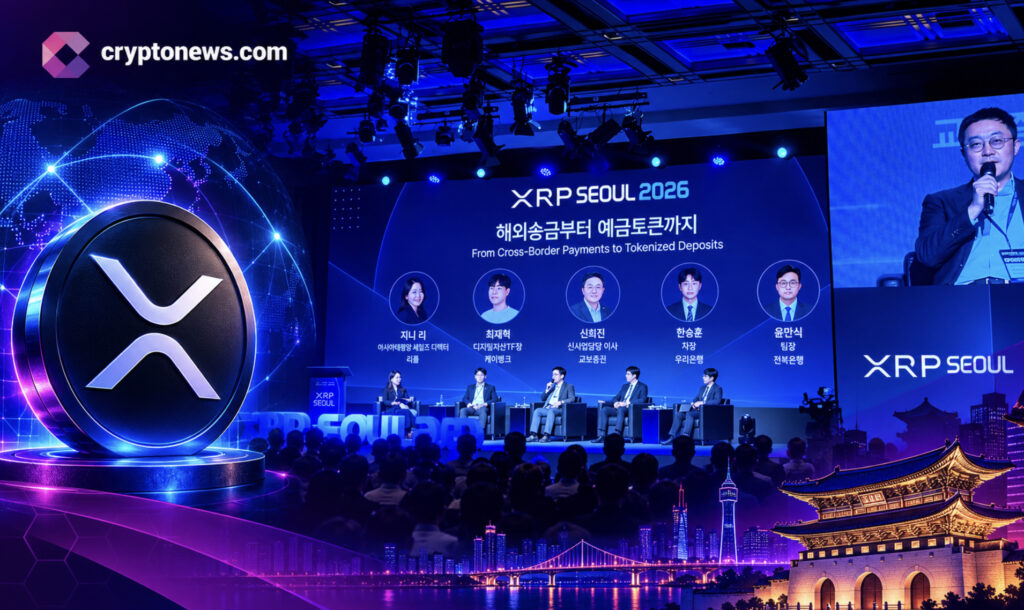
Four Korean financial institutions appeared alongside Ripple at XRP Seoul 2026, igniting news and speculation on Ripple’s reach. As of today, Jeonbuk Bank has planned Ripple Payments deployment, and Kbank’s custody and remittance initiatives are documented.
Ripple introduced XRP Asia at the Seoul event as a regional initiative to promote the XRP Ledger. In an August 18, 2026 announcement, Ripple said Jeonbuk Bank would deploy Ripple Payments for cross-border business remittances. The company described it as the first regional bank in Korea to deploy the service, which is intended to provide near-real-time settlement.
Kbank has two distinct Ripple-related initiatives in the source account: a remittance pilot targeting the UAE and Thailand, and institutional wallet-as-a-service infrastructure through Ripple Custody. Ripple’s announcement on Kbank’s custody infrastructure describes a service for managing digital assets.
The other relationships also require careful attribution. The event account connects Kyobo Life, associated with Kyobo Securities, to work on tokenized government-bond settlement, while Woori Bank is described as working with Korean custodian BDACS, which manages XRP for institutional clients.
Payment Software, Custody News, and XRP Settlement
Ripple Payments can coordinate cross-border transfers using conventional currencies such as dollars, won, or yen. Depending on transaction design, the service may also use RLUSD or XRP, so deploying Ripple Payments alone does not reveal which asset settles a particular flow.
A separate bridge-asset model converts value into XRP, moves it through the XRP Ledger, and converts it into the destination currency. That structure can seek to reduce the need to hold funds in advance with foreign intermediary banks, but the Seoul disclosures do not confirm that any participating bank has adopted it.

Ripple Custody addresses a different function: storing and managing digital assets for institutional use. Institutional custody infrastructure can expand a bank’s ability to handle digital assets without indicating which assets will be used for payments; likewise, a custodian holding XRP for clients does not prove payment demand.
The same distinction applies to tokenization initiatives, where use of Ripple-linked infrastructure does not by itself confirm XRP settlement.
For XRP, the event is evidence of Ripple’s expanding institutional relationships in South Korea, not a disclosed demand catalyst. A stronger adoption signal would require an explicit settlement-asset designation and measurable transaction flows or a volume commitment; neither appears in the available announcements.